Showing posts with label arbitration. Show all posts

Monday, May 31, 2021

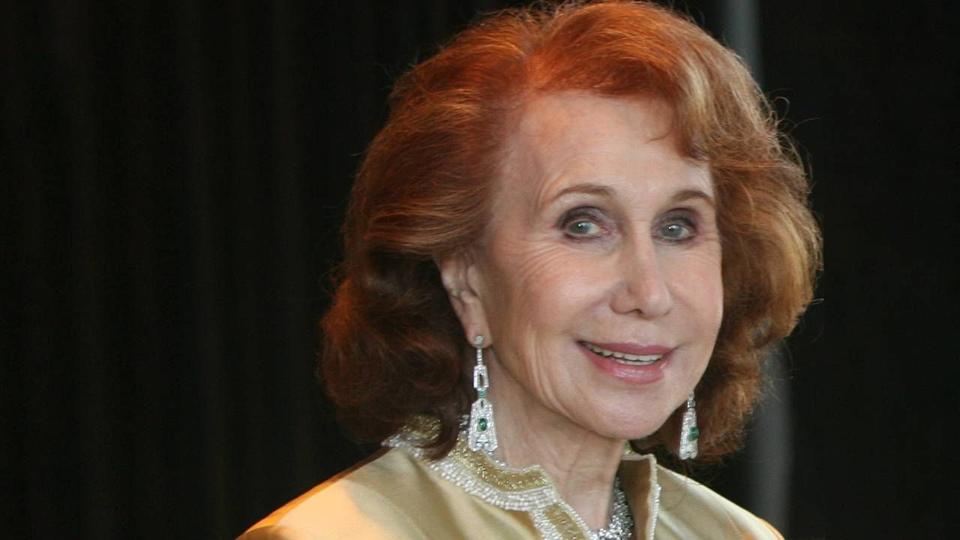
The Grandmother Who Won Her Elder Fraud Case Against Her Grandsons

By Richard Eisenberg

The Beverley Schottenstein $80 million elder financial fraud story is one you won't believe. But, as my "Friends Talk Money" podcast co-hosts and I explained in our two latest episodes, it's one you need to know about to protect your parents from becoming victims themselves.

Schottenstein, 94, recently won $19 million in her arbitration case against J.P. Morgan Securities and her grandsons Avi and Evan Schottenstein, her brokers there for five years, ostensibly managing her millions. (Schottenstein is matriarch of the family's Columbus, Ohio retail dynasty, whose stores included Value City and American Eagle Outfitters AEO -1.5%.)

Problem is, the grandsons wouldn't tell their grandmother what stocks they were buying and selling. They made hundreds of transactions this way, Schottenstein said.

"I would call and say, 'Now, what's going on, boys? I want to know.'" Schottenstein, who lives in Florida, told "Friends Talk Money" co-host Pam Krueger. (You can listen to the whole episode wherever you get podcasts.)

But, Schottenstein said, her grandsons told her only that they were doing well for her.

When the Brokerage Statements Stopped Coming

After Schottenstein insisted they check with her before trading in her account, her brokerage statements stopped coming. When she complained about that to her grandsons and got no satisfaction, Schottenstein got J.P. Morgan Chase CEO Jamie Dimon on the phone.

"I was very upset talking to Jamie," Schottenstein recalled. "He said: 'I'm going to let you talk to my Number One Man." She then spoke to that man, told him her story and started crying. "And he said: 'I'm going to take care of it immediately. Don't worry. Don't worry.' I never heard back from any of them."

Ultimately, Schottenstein went to arbitration through FINRA (Financial Industry Regulatory Authority) because retail investors can't take their brokers to court.

"J.P. Morgan made millions of dollars just in commissions and those commissions were also split with Evan and Avi," Schottenstein's granddaughter Cathy, a first cousin of Avi and Evan Schottenstein, said on the podcast. She's writing a book about the case and her grandmother, who she calls Nanny ("Twisted: Conflict, Madness and the Redemptive Power of a Granddaughter's Love"). 

Schottenstein's granddaughter sad that at one point, J.P. Morgan Securities froze her grandmother out of her own account and that the grandsons wrongly said she had dementia.

"Friends Talk Money" co-host Terry Savage said that after Schottenstein persevered and won the case in February 2021, J.P. Morgan Chase issued a statement saying that "the brokers involved are no longer with our firm" and "do not reflect the values of our firm." The grandsons' attorney said the $19 million award was inconsistent with the evidence presented at the FINRA hearing. 

FINRA permanently banned Evan Schottenstein in April 2021. The Schottenstein brothers have asked a court to nullify the arbitration panel's ruling.

The Lousy Odds of Winning in Arbitration

Most investors going through FINRA arbitration — where decisions are final — don't win a dime. When I checked the FINRA site, I learned that customers were only awarded damages 32% of the time in 2020, and that's down from 45% in 2019.

Even if you do win, Louis Straney, managing partner at the Arbitration Insight firm in Lamy, N. M., told "Friends Talk Money," you're "seldom fully made whole, because of attorney's fees and litigation costs and other expenses." The average filing fee with FINRA is about $1,200; the larger the case, the higher the fees, according to Investorlawyers.com.

The new Securities and Exchange Commission Chair Gary Gensler recently told Congress he favored legislation known as the Investor Choice Act that would let investors take brokers to court rather than arbitration.

Schottenstein's case and the FINRA arbitration realities show why it's so important for investors to watch their brokers like a hawk. And if they spot irregularities — such as churning of their accounts through excessive trading — they need to report this to the firm and to financial authorities.

"It's important that you have someone on your side to speak up," said Savage. And, she advised, put your accusations about unauthorized trading in writing.

First, send them to the brokerage firm's branch manager. If you get no results, Savage said, take it up the chain of command.

"Don't be shy about reaching out to the state securities administrator," said Krueger. "It's really important that people can recognize the red flags and follow in Beverley's footsteps and speak up."

Savage noted that the FINRA site's BrokerCheck area can also tell you whether there have been regulatory actions, arbitration cases and complaints against a broker.

Elder Financial Abuse: A $3 Billion Problem

While the dollars in Schottenstein's case may be astronomical, elder financial abuse is a serious problem for many mere older mortals on the planet. As Savage noted: "It's such a sad story. And unfortunately, it's not all that uncommon."

Estimates of elder financial fraud and abuse vary, but the Federal Bureau of Investigation said older Americans suffered $3 billion in losses in 2019. The average loss per case: about $18,000.

"About ninety percent of perpetrators of elder financial abuse are actually the children of the spouses or the caretakers," said Savage. But, I noted, many of these cases aren't reported because the victims are embarrassed or humiliated or they don't want to get a loved one in trouble or cause a family rift.

Schottenstein told "Friends Talk Money" that the whole financial exploitation experience was very upsetting for her. "I started losing my hair," she said. "Thank goodness it's coming back to me."

Full Article & Source:

Thursday, January 24, 2019

Wells Fargo Lawsuit Defendants Counter Septuagenarian's Elder Abuse Claims

Wells Fargo-related defendants recently filed a motion to compel a 70-plus-year-old woman who suffers from cognitive decline to arbitrate privately (rather than in a public courtroom) the financial elder-abuse claims she has filed against the wirehouse defendants. The move illustrates a continuing trend of big firms maneuvering to keep litigation out of public arenas and in control of industry forums such as Finra arbitration.

With their motion, the Wells Fargo defendants counter allegations that the woman, Karen Thompson, made in her federal lawsuit. Specifically, Thompson alleges in her lawsuit that the Wells Fargo defendants, as many as 100 employees, and her own advisor, Russell Wixon (with whom she had maintained a 30-year-long client relationship and who is a Wells Fargo managing partner) all engaged in financial elder abuse.

Thompson, whose lawsuit was transferred in November from state to federal court in California, alleges that because of her age and disability she was vulnerable to scammers who had her wire what ultimately amounted to her entire life savings — about $660,000 — from her Wells Fargo accounts to Costa Rica.

Wixon, other Wells Fargo employees, the bank, and the advisory firm allowed that fraud to take place — despite Wells Fargo’s marketing claims that its advisors are “intimately acquainted” with their clients’ financial goals and concerns, according to Thompson’s lawsuit.

In their motion, however, the Wells Fargo defendants allege that when Thompson instructed her bank to wire money to the Costa Rican recipient, she was repeatedly asked about “the purposes and bona fides of the transactions.” In response, Thompson provided “detailed, fact-specific assurances that the transactions were for legitimate purposes, including paying college tuition for her nephew and for non-FDA approved pancreatic cancer treatments for her sister-in-law, whom she identified by name,” the Wells Fargo defendants’ motion states.

Thompson filed a report to the Contra Costa County Sheriff’s Department stating “she had no intention of using the money for those purposes; rather, she says, fraudsters conned her into believing she was helping to build a school for needy children, and persuaded her to try to mislead Wells Fargo to avoid arousing its suspicions,” according to the Wells Fargo defendants’ motion.

Thompson “now seeks to recover her losses from Wells Fargo on the theory that it should have refused to follow her own instructions about what to do with her own money,” the motion states. Therefore, her claims “are simply not viable,” the motion states.

Without ruling on her claims’ viability, however, the court should send them to arbitration where they belong, based on agreements Thompson signed to attempt to first resolve such disputes privately, the motion states. The Wells Fargo defendants ask the court not only to compel Thompson to arbitrate, but also to halt the federal litigation until the outcome of that private proceeding.

Wirehouses and other large financial firms often try to keep conflicts out of public courts and in arbitration — whether the plaintiff be a client or even the defendant’s own employee.

And in the past decade, federal court rulings have made it more likely all plaintiffs may be compelled to arbitrate. Since 2010, the U.S. Supreme Court has decided no fewer than 13 opinions that interpreted the Federal Arbitration Act, according to a paper entitled “Arbitration Nation,” published in 2018 and written by David Horton and Andrea Cann Chandrasekher, both University of California at Davis School of Law professors. The Supreme Court justices have consistently ruled that the FAA trumps state efforts to regulate arbitration and lets companies extricate themselves from class action litigation with arbitration waivers, according to their paper.

Linda Friedman, a law partner in Chicago’s Stowell & Friedman, says arbitrations where “there are no rules and no exposure” are inherently disheartening for plaintiffs — even when they win. “Federal court is no panacea,” for plaintiffs either, but it’s better than arbitration overall, Friedman told FA-IQ previously.

In her lawsuit, Thompson alleges that the Wells Fargo defendants permitted the Costa Rican-based scammers to succeed, even though Thompson had never engaged in similar transactions in the 10 years of doing business with Wells Fargo Advisors, 20 years with Wells Fargo bank, and 30 years with Wixon.

She alleges that two years ago, in November 2016, she suddenly and uncharacteristically began to withdraw large sums — between $29,000 and $108,000 — from her retirement accounts and send them to her Wells Fargo checking accounts. She would then go into the bank’s branch offices and request to transfer those sums by wire to Costa Rica, according to her lawsuit. Thompson repeated that pattern 12 times, according to her lawsuit.
 
In her prior 20 years of banking with Wells Fargo, she had “never engaged in a single transaction in which she was sending any money, let alone huge sums, to a third party in a foreign country,” her lawsuit states.

Those withdrawals and wire transfers “each constituted a profound change in her banking pattern,” her lawsuit states. “Yet despite all these hallmarks of financial elder abuse, [Wells Fargo] defendants did nothing to stop it — nothing. Instead, defendants just continued to proactively take money out of her accounts and knowingly assist the blatant financial elder abuse of their long-time customer until all of her life savings was gone,” Thompson’s lawsuit states.

A Wells Fargo spokesperson declined to comment on the litigation.

Lawyers from the Los Angeles-based law firm Munger, Tolles & Olson, which represents the Wells Fargo defendants, did not respond to a request for comment.

Thompson’s lawyer at San Francisco-based firm Stebner and Associates also did not respond to a request for comment.

Full Article & Source:
Wells Fargo Lawsuit Defendants Counter Septuagenarian's Elder Abuse Claims